Corporate tax in the Gulf and Middle East: 13 countries compared
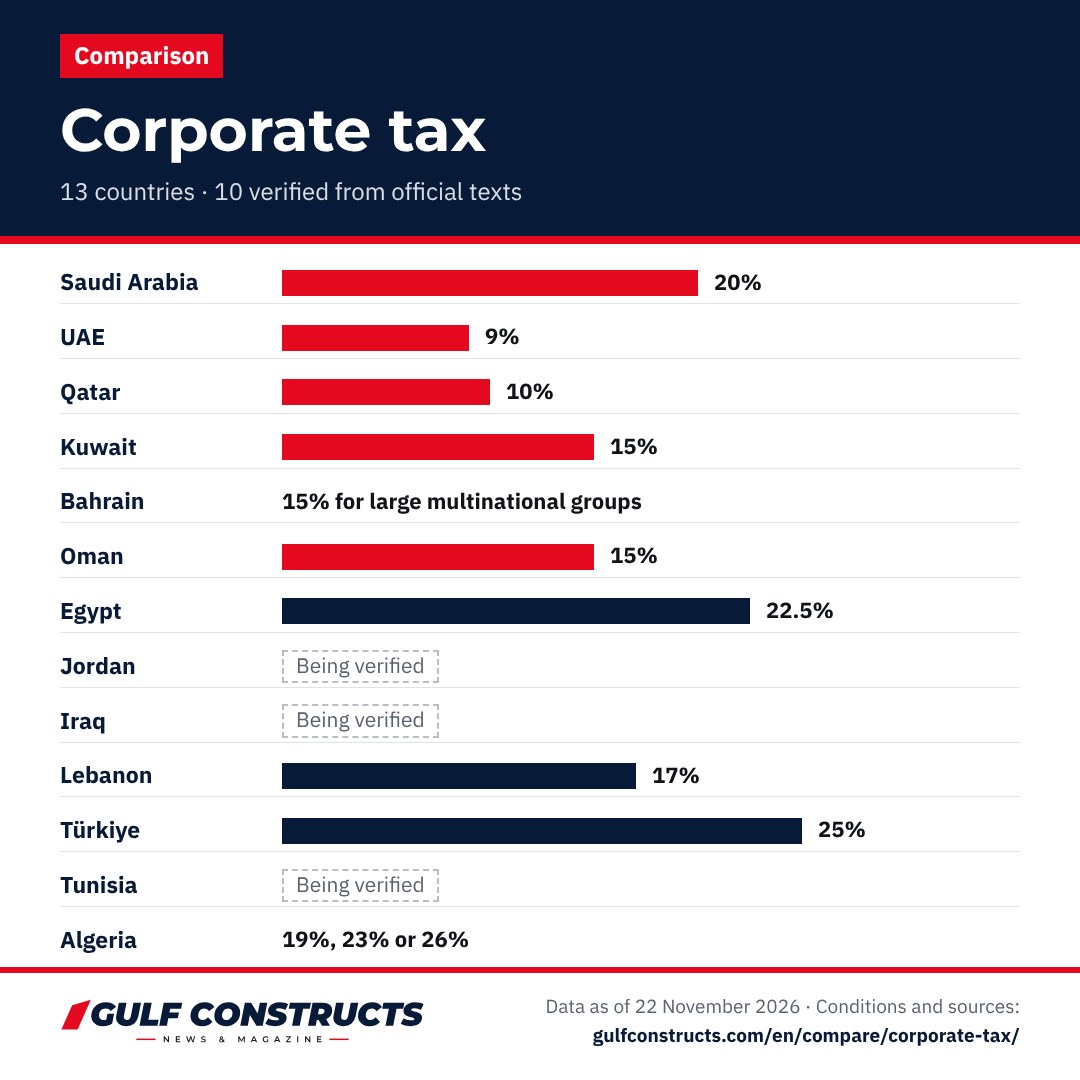
Corporate tax in every country we cover, from the official text. We have verified 10 of 13 countries so far; the rest are marked “under verification” until we read the source.
Gulf states
| Country | Corporate tax | Details as in the source |
|---|---|---|
| Saudi Arabia | 20% | Income tax on non-Saudi shares in resident companies; the share of Saudis and GCC nationals treated as Saudis is subject to zakat at 2.5%. Oil and hydrocarbon production has rates from 50% to 85%.12 |
| UAE | 9% | On taxable income above AED 375,000 and 0% below it, for tax periods starting on or after 1 June 2023.34 |
| Qatar | 10% | On net income generated in Qatar, and 35% for oil and petrochemicals. Qatari partners are exempt; foreign partners pay 10% on their share of net profit.5 |
| Kuwait | 15% | On net taxable income of foreign companies. According to KDIPA there is also a 2.5% National Labour Support Tax on profits of listed companies, and 1% zakat and a 1% KFAS contribution on profits of shareholding companies.67 |
| Bahrain | 15% for large multinational groups | Domestic Minimum Top-up Tax: levied on Bahrain entities of multinational groups with global revenue of EUR 750 million or more in at least two of the four preceding financial years, for financial years starting on or after 1 January 2025. We have not yet verified the position of other companies.8 |
| Oman | 15% | Of net taxable income for establishments and commercial companies; 3% for small enterprises meeting conditions; 55% for oil and gas exploration companies under concession contracts.9 |
Middle East
| Country | Corporate tax | Details as in the source |
|---|---|---|
| Egypt | 22.5% | Tax on the profits of companies operating in Egypt, according to GAFI. The Investment Law deducts 50% or 30% of investment costs from taxable net profits for up to seven years, depending on the geographic sector and project type.1011 |
| Jordan | Under verification | Being verified against the official source. |
| Iraq | Under verification | Being verified against the official source. |
| Lebanon | 17% | On the profits of joint stock and limited liability companies, with 15% on profits from selling fixed assets including shares and a 10% withholding tax on dividends and interest. Holding and offshore companies are exempt from income tax on profits and follow special rules.12 |
| Türkiye | 25% | On corporate profits (Article 32 of Corporate Tax Law No. 5520 as amended by Law No. 7456 of 14 July 2023), and 30% for banks, insurers and specified financial institutions. According to the Investment Office, exporters get a reduced 5% rate on export income.1314 |
North Africa
| Country | Corporate tax | Details as in the source |
|---|---|---|
| Tunisia | Under verification | Being verified: we are checking the latest finance law in the official text. |
| Algeria | 19%, 23% or 26% | Article 150 of the Direct Taxes Code: 19% for producing goods, 23% for building, public works, hydraulics, tourism and spa activities (excluding travel agencies), and 26% for other activities.15 |
Calculate corporate tax on your profit All criteria in one table Embed this table on your site
This comparison as an image
Other criteria
- VAT
- Foreign ownership
- Investment legal framework
- Foreign property ownership
- Investor residency
- Free & economic zones
Sources
- Simplified Guideline for Income Tax, second version — ZATCA (May 2026)
- Implementing Regulations for Zakat Collection 1445H — ZATCA (2024, amended 1446H)
- Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses — Ministry of Finance (December 2022)
- Cabinet Decision No. 116 of 2022 — Ministry of Finance (2022)
- Investors guide — General Tax Authority, Qatar (Official page)
- Law No. 2 of 2008 amending Kuwait Income Tax Decree No. 3 of 1955 — published by KDIPA (2008)
- Invest in Kuwait brochure — KDIPA (November 2025)
- National Bureau for Revenue — Domestic Minimum Top-up Tax FAQs (in Arabic) (page last updated 19 November 2026)
- Tax rates — Oman Tax Authority portal (Official page)
- Snapshot of Egypt — General Authority for Investment and Free Zones (2022 edition)
- Investment Law No. 72 of 2017 — GAFI English translation (including Law No. 160 of 2023 amendments)
- Tax system — Investment Development Authority of Lebanon (IDAL) (Official page)
- Corporate Tax Law No. 5520 — Turkish legislation portal (Turkish) (Consolidated text with amendments)
- Tax guide — Investment Office of the Presidency of Türkiye (Official page)
- Tax system — Algerian Investment Promotion Agency (AAPI) (French) (Official page)
Sources accessed:
Published content is for general information only and is not investment advice.